Deal Teams: Draft Working Capital Clauses for the 60–90 Day True Up
A working capital adjustment is a dollar-for-dollar true-up to the purchase price that compares actual closing working capital to a negotiated target: excess raises the price, a shortfall reduces it. This usually plays out in two moves: an estimate at closing, then a final true-up 60 to 90 days later once the dust settles on the books.
TL;DR:
Accurate agreement on which accounts and components count toward working capital is crucial to prevent disputes over inclusion or exclusion of items like customer deposits or deferred revenue.
The measurement period for establishing the target should reflect normal business operations, typically averaging over six to twelve months or using a forecast for fast-growing companies.
The final true-up process involves an estimate before closing, followed by a detailed review within 60 to 90 days, with strict deadlines to avoid waivers or disputes.
Drafting precise clauses—defining the methodology, inspection rights, and dispute resolution procedures—and attaching calculation examples as exhibits can reduce post-closing conflicts significantly.
Engaging legal and accounting professionals early, with clear scopes and pre-agreed accountants, improves the accuracy and efficiency of working capital adjustments and true-ups.
Chief Legal OfficeKeep Your Deal Moving After ClosingChief Legal Office provides senior legal leadership and a dedicated team to help manage complex transactions and ongoing legal work.Explore Chief Legal Office
Table of Contents
How the math actually works: a worked example
What counts: components in and out of the calculation
Setting the target and choosing the right measurement window
What happens after closing, and when
Drafting checklist: the clauses that prevent fights later
Where these deals go wrong: lessons from a real fight
Keeping working capital consistent with tax allocation
Negotiation moves both sides should make
What an embedded legal team actually does with this mechanism
Getting the true-up right without doing it alone
Primary sources worth reading directly
Sources
FAQ
How the math actually works: a worked example
Most agreements use one of two structures. The one-step approach adjusts the price once, at closing, based on an estimate. The two-step approach, which is far more common, estimates at closing and then true-up after closing based on actual numbers.
The formula itself is simple:
Adjusted Price = Base Price + (Actual Working Capital minus Target Working Capital)
If Actual Working Capital is below Target, the seller pays the buyer the difference
If Actual Working Capital is above Target, the buyer pays the seller the difference
Say a deal has a base price and a negotiated target in working capital. If the seller delivers the business with actual working capital above the target at closing, the seller is owed the difference. If actual working capital comes in below the target, the buyer gets a corresponding credit.
Collars and caps change the outcome in practice. A collar might say no adjustment happens unless the swing exceeds $50,000, which keeps small, immaterial fluctuations from triggering paperwork and arguments nobody wants to have.
What counts: components in and out of the calculation
The target and actual numbers only mean something if both sides agree on what is being measured. That sounds obvious until you are three weeks into a dispute over whether a customer deposit belongs in the calculation.
Items usually included:
Accounts receivable, net of a reasonable allowance for doubtful accounts
Inventory, valued consistently with how the seller has always valued it
Prepaid expenses and other current assets tied to ongoing operations
Accounts payable and accrued liabilities incurred in the ordinary course
Items usually excluded:
Cash and cash equivalents, which are typically handled separately in the price
Interest-bearing debt and long-term liabilities, which get paid off or assumed outside the working capital bucket
Deferred revenue, payroll accruals, and customer deposits cause the most fights because reasonable accountants can classify them differently depending on the business. The ABA’s analysis of working capital adjustments recommends attaching a schedule at the trial balance level so both sides are working from the same list of accounts, not a general reference to “GAAP” that each side interprets in its own favor.
Pro Tip: Attach the schedule as an exhibit, not a defined term buried in the agreement’s body. People read exhibits. They skim definitions.
Setting the target and choosing the right measurement window
A working capital target should reflect what the business normally needs to run, not a number either side picked because it made the price look better. The standard approach, per the ABA’s guidance on working capital planning, is to average month-end working capital over six to twelve months to smooth out seasonality.
A landscaping company with heavy summer receivables needs a target that reflects its full cycle, not just its best month
A company growing quickly might be better served by a forecast-based target, since historical averages understate what the business will actually need going forward
Collars and floors can be layered on top of either approach to limit how much a short-term anomaly affects the final price
Get the measurement period wrong and you bake a structural problem into the deal before either side has signed anything.
What happens after closing, and when
The mechanics follow a fairly standard sequence, and the timing matters because missing a deadline can waive your right to object.
A few days before closing, the seller delivers an Estimated Closing Statement, which sets the initial purchase price adjustment
Within roughly 60 to 90 days after closing, the buyer delivers its own Closing Statement with supporting detail, prepared in good faith rather than to any particular outcome
The seller then gets a review period, commonly 30 days, to inspect the buyer’s work and raise objections
Sample language from a recent SEC-filed acquisition exhibit follows exactly this shape: an Estimated Statement near closing, a Buyer Closing Statement within about 90 days, and a 30-day seller review window before unresolved items go to an independent accountant. If the seller misses the objection window, the buyer’s numbers typically become final, so counsel on both sides should calendar that deadline the day the agreement is signed.
Drafting checklist: the clauses that prevent fights later
Good working capital clauses are specific to the point of being almost boring. That is the goal. Ambiguity is what creates six-figure disputes over a $40,000 deferred revenue entry.
Require a Working Capital Methodology Schedule that defines every included account, tied to a Reference Balance Sheet from an agreed date
Spell out Estimated versus Actual mechanics separately, including exact delivery timing and what supporting detail must accompany each statement
Give the reviewing party real inspection rights, meaning access to work papers and underlying ledgers, not just a summary page
Define shortfall mechanics precisely: does payment come from escrow first, and what happens if escrow is insufficient
Name the independent accounting firm in advance, instruct it to act as an expert rather than an arbitrator, and limit its scope to the specific disputed line items
One of the most reliable fixes for post-closing disputes, according to the ABA’s drafting analysis, is attaching an illustrated example calculation as an exhibit so both parties have already agreed, on paper, what the math looks like before a real dispute ever arises.
Where these deals go wrong: lessons from a real fight
Perimeter and definition disagreements, meaning arguments over which accounts belong in the calculation, are the leading cause of post-closing disputes. The dispute between Save Mart and Kingswood Capital is a useful cautionary tale here: the ABA’s analysis of that case shows how inconsistent schedules and unclear definitions escalated into a major post-closing claim and arbitration, the kind of outcome that costs far more in legal fees than the disputed amount itself.
A few guardrails consistently reduce that risk:
Pre-name the independent accountant in the agreement rather than negotiating that choice after a fight has already started
Instruct the accountant narrowly, as an expert resolving specific numbers, not as an arbitrator deciding broader contract disputes
Set a de minimis threshold so disputes under a defined dollar amount simply do not get litigated
Size the escrow to match realistic adjustment exposure, not an arbitrary round number
Precise drafting up front is cheaper than reconstructing intent after the relationship has soured.
Keeping working capital consistent with tax allocation
Here is a trap that catches even experienced deal teams: the same assets and liabilities sometimes get classified differently for tax purchase-price allocation than they do for the working capital true-up. One agreement calls a reserve a liability, the allocation schedule treats it differently, and now you have two documents quietly contradicting each other.
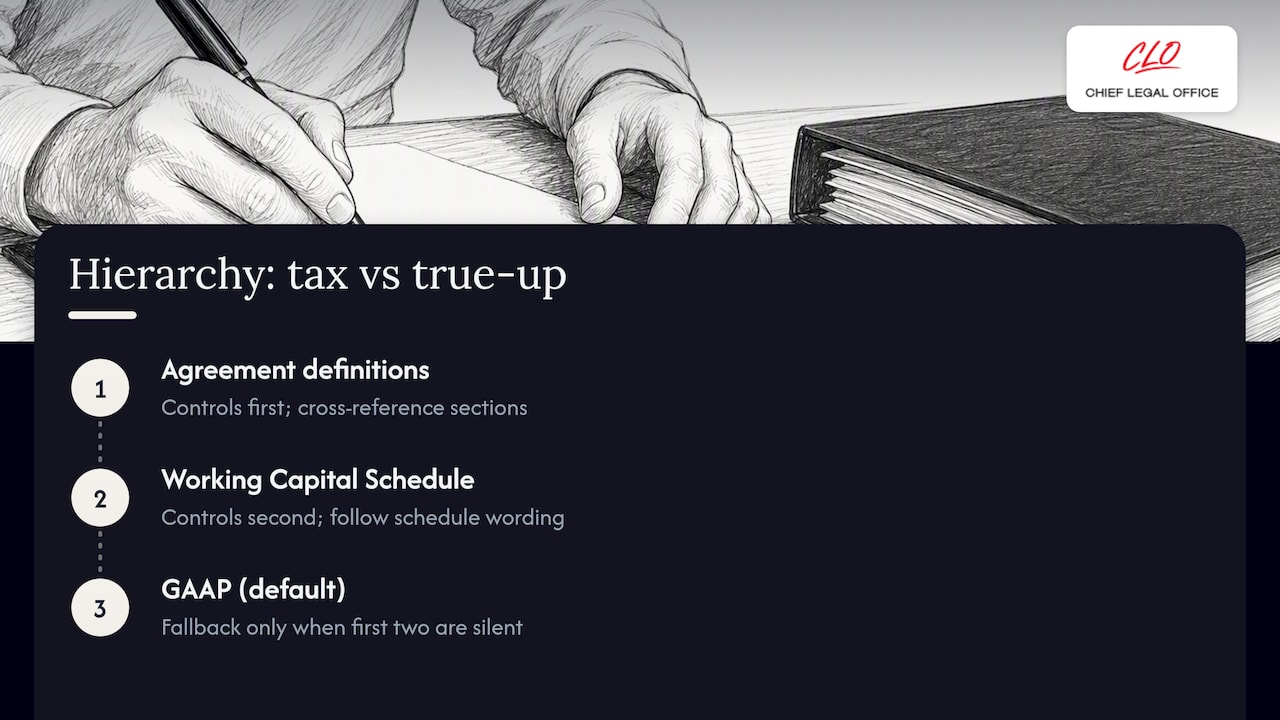
The ABA’s guidance on purchase-price allocation recommends setting a clear hierarchy: agreement definitions control first, then the Working Capital Methodology Schedule, then GAAP as a default only where the first two are silent. Cross-reference the sections explicitly. And get your tax advisor, deal counsel, and accountant talking to each other at the drafting stage, not after the IRS or the other side’s accountant flags the inconsistency.
Negotiation moves both sides should make
Several terms in the working capital mechanism are genuinely negotiable, and who wins each one shapes the deal’s real economics far more than the headline price does.
Decide early who prepares the Closing Statement; buyers usually do, so sellers should negotiate strong review and inspection rights in exchange
Negotiate the measurement period, the escrow size, the collar width, and the de minimis threshold as a package, not line by line
Agree on the independent accountant’s identity and instructions before anyone needs them
Sellers should request a trial run of the calculation using recent financials well before signing, so there are no surprises in methodology. Buyers should insist on access to supporting ledger detail, not a summary statement, since that is where disputed items hide.
Pro Tip: Ask for a sample Closing Statement calculation during due diligence. If the other side can’t produce one cleanly, that tells you something about how clean the post-closing process will be.
What an embedded legal team actually does with this mechanism
Years of reviewing these clauses taught me that the real risk rarely shows up in the definitions section. It shows up in the gap between signing and closing, when nobody owns the follow-through. An embedded team that already knows the business can turn around a Closing Statement review in days instead of weeks, because the schedule, the accountant relationship, and the escalation plan were built before the dispute clock started running.
— Amy Natasha Osteen
Getting the true-up right without doing it alone
Chief Legal Office’s Capital Raises and M&A support exists for exactly this moment: drafting the Working Capital Methodology Schedule, staffing the Closing Statement review, and coordinating with your accountant and the independent accounting firm if a dispute escalates.
Clients get a drafted schedule tied to a Reference Balance Sheet, a reviewed Closing Statement with documented findings, and an escalation plan that names the accountant and limits scope before anything goes sideways. If you want ongoing coverage for deals like this one, compare engagement models on our pricing page, or reach out about Fractional General Counsel support for your next transaction.
Primary sources worth reading directly
ABA Business Law Today for drafting and dispute guidance
SEC exhibit filings showing operative clause language
A practical closing process guide for small business sellers
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
What are working capital adjustments?
A working capital adjustment is a post-closing true-up that compares the business’s actual working capital at closing to a negotiated target, with the difference paid as a price adjustment. It protects the buyer from inheriting a business stripped of the cash and inventory it needs to run day to day.
Is higher or lower net working capital better?
Neither is inherently better; what matters is whether actual working capital matches the negotiated target. Working capital above target typically means the seller receives additional payment, while working capital below target typically means the buyer receives a credit.
How do you calculate a working capital adjustment?
The basic formula adds or subtracts the difference between actual and target working capital from the base purchase price. Most deals use a two-step process: an estimate near closing, then a final calculation within about 60 to 90 days afterward based on the actual Closing Statement.
What is adjusted working capital?
Adjusted working capital refers to the final working capital figure used in the purchase price true-up after applying the agreement’s specific inclusions, exclusions, and any negotiated normalization adjustments. It is defined by the Working Capital Methodology Schedule attached to the agreement, not by a generic accounting formula.
Recommended
The lawyerly fine print: This article is for general information, not legal advice…