Equity Compensation Agreements: The U.S. 83(b) Deadline Is 30 Days
Check the grant agreement and the equity plan before you trust anything else, including the offer letter, because those two documents decide who actually receives equity, when it vests, and what tax rules apply. Confirm four things immediately: the award type, the vesting schedule, the fair market value used at grant, and the post-termination exercise window. If anything looks inconsistent with SEC or IRS rules, that is worth a second look before anyone signs.
TL;DR:
ISOs are limited to employees, and a $100,000 annual vesting cap preserves favorable tax treatment; consultants and advisors generally need NSOs instead.
Restricted stock recipients must file an 83(b) election within 30 days; RSUs generally do not qualify because shares are issued only at vesting.
A 90 day post termination exercise window can erase vested options if you cannot pay promptly, so confirm its exact terms and any change of control triggers.
Private companies must provide added Rule 701 disclosures when compensatory sales exceed $10 million in any 12 month period; track cumulative grants, not individual awards.
Chief Legal OfficeKeep Equity Agreements on TrackChief Legal Office provides a fractional in-house legal department to help growing technology companies manage legal work as they scale.Learn about Chief Legal Office
Table of Contents
Types of Equity Awards and Who They Fit
Key Drafting Checklist: Clauses to Read Before You Sign Anything
Vesting Schedules and Acceleration: What’s Standard and What’s Negotiable
Tax Timing: ISOs, NSOs, RSUs, and the 83(b) Decision
Rule 701 and Form S-8: Keeping Equity Grants Within SEC Limits
How We Review and Fix Equity Documentation
Post-Vesting Actions: Exercise, Payment, and Share Issuance
Compliance and Reporting Obligations Beyond 409A and Rule 701
Amending Equity Agreements: What Changes and What It Takes
Fitting Equity Into the Broader Compensation Package
What Founders Should Prioritize Right Now
How We Help With Equity Compensation Agreements
FAQ
Sources
Types of Equity Awards and Who They Fit
Most confusion about equity compensation starts with a basic mismatch: the recipient thinks they got “stock,” but the paperwork says something more specific, and that specificity controls everything from tax timing to what happens if the company gets sold.
Incentive stock options (ISOs) can only go to employees, never consultants or advisors, and they carry potential favorable tax treatment if the holder meets specific holding periods. Nonqualified stock options (NSOs) can go to anyone, employees, consultants, board members, and they create ordinary income on exercise without the same holding period perks. Restricted stock is actual stock issued upfront, subject to a vesting schedule and a company right to buy it back if the holder leaves before vesting. Restricted stock units (RSUs) are a promise to deliver shares later, usually at vesting, with no stock actually issued until that point. Stock appreciation rights (SARs) pay out the increase in value without requiring the holder to buy anything. Phantom stock mimics stock ownership economically but never issues real equity, which matters for cap table math and investor diligence.
Why this matters practically:
ISOs require employee status and a $100,000 annual vesting limit to keep favorable tax treatment intact.
NSOs work for anyone the company wants to incentivize, including outside advisors and board members.
Restricted stock recipients should evaluate an 83(b) election within 30 days of the grant, a deadline the IRS enforces strictly with no extensions.
RSUs generally make an 83(b) election irrelevant because no stock exists until vesting.
Phantom stock and SARs avoid dilution concerns but don’t give the holder actual ownership or voting rights.
Founders sometimes default to whatever template their lawyer used for the last hire, without asking whether an NSO or restricted stock grant fits that specific role better. It’s worth asking the question every time, because the wrong award type is hard to unwind later without a taxable event.
Key Drafting Checklist: Clauses to Read Before You Sign Anything
A grant agreement and plan document are long, but you don’t need to read every word. You need to find a handful of clauses and understand exactly what they say, because these are the provisions that generate disputes later.
Grant date and number of shares or options. Confirm the date matches board approval, not just the offer letter date.
Exercise price. This should equal the fair market value on the grant date, supported by a 409A valuation.
Vesting schedule and cliff. Look for the start date, the cliff length, and whether vesting is monthly or quarterly after the cliff.
Post-termination exercise (PTE) window. This is how long you have to exercise vested options after leaving, and it varies widely.
Change of control treatment. Does vesting accelerate, and under what conditions?
Repurchase rights. Can the company buy back unvested or even vested shares, and at what price?
Transfer restrictions. Most private company equity can’t be sold or transferred without company consent.
Definitions of “Cause” and “Good Reason.” These terms drive acceleration and severance outcomes, and vague drafting here causes real fights.
Ambiguous termination language is where a lot of equity disputes actually live. “Cause” defined as “any reason the board determines in its discretion” gives the company enormous leverage. “Good Reason” that requires the employee to prove constructive termination through a multi-step notice and cure process can quietly eliminate the protection it appears to offer.
When the offer letter, the grant agreement, and the plan document disagree, the formal plan and grant agreement typically control, not the offer letter, according to practitioner commentary tracking recent SEC guidance updates. Founders who made informal promises in an offer letter should reconcile that language into the actual grant documents instead of assuming the informal version holds up.
Pro Tip: Read the PTE window before you read the vesting schedule. A great grant with a 90-day exercise window can cost a departing employee their entire equity stake if they can’t afford to exercise in time.
Vesting Schedules and Acceleration: What’s Standard and What’s Negotiable
A four-year vesting schedule with a one-year cliff remains the default structure across most of the U.S. Variations exist, but this is still the pattern most companies start from and most investors expect.
Acceleration provisions are where the real negotiation happens, and the market standard is clearer than most people expect:
Double-trigger acceleration is the norm: vesting speeds up only when a change of control happens and the employee is terminated without Cause or resigns for Good Reason within a defined window, according to market practice guidance on acceleration clauses.
Single-trigger acceleration, where a sale alone vests everything, is uncommon because acquirers dislike inheriting a workforce with no retention incentive left.
The precise window matters enormously: “terminated within 90 days of the change of control” protects far less than “terminated within 12 months,” and that language should tie clearly to the closing date and the termination notice date.
PTE windows can shift during a financing or acquisition, so it’s worth confirming whether the agreement locks in the original window or allows board discretion to shorten it.
If you’re negotiating an offer and the company mentions acceleration casually without putting numbers on it, ask for the specific trigger language in writing. We’ve reviewed change of control clauses where a single missing word turned a 12-month protection window into a 90-day one.
Tax Timing: ISOs, NSOs, RSUs, and the 83(b) Decision
Every equity award creates a tax event somewhere, and the agreement’s structure determines when that event happens and how much it costs.
NSO exercises generally create ordinary income on the spread between the exercise price and fair market value at the time of exercise, according to IRS guidance on stock option taxation. ISOs can avoid ordinary income at exercise but may trigger alternative minimum tax, and they carry specific holding-period rules to qualify for favorable long-term capital gains treatment on sale. RSUs are taxed as ordinary income when they vest, regardless of whether the holder sells the shares, which often creates a cash flow problem for employees who owe tax on stock they haven’t sold yet.
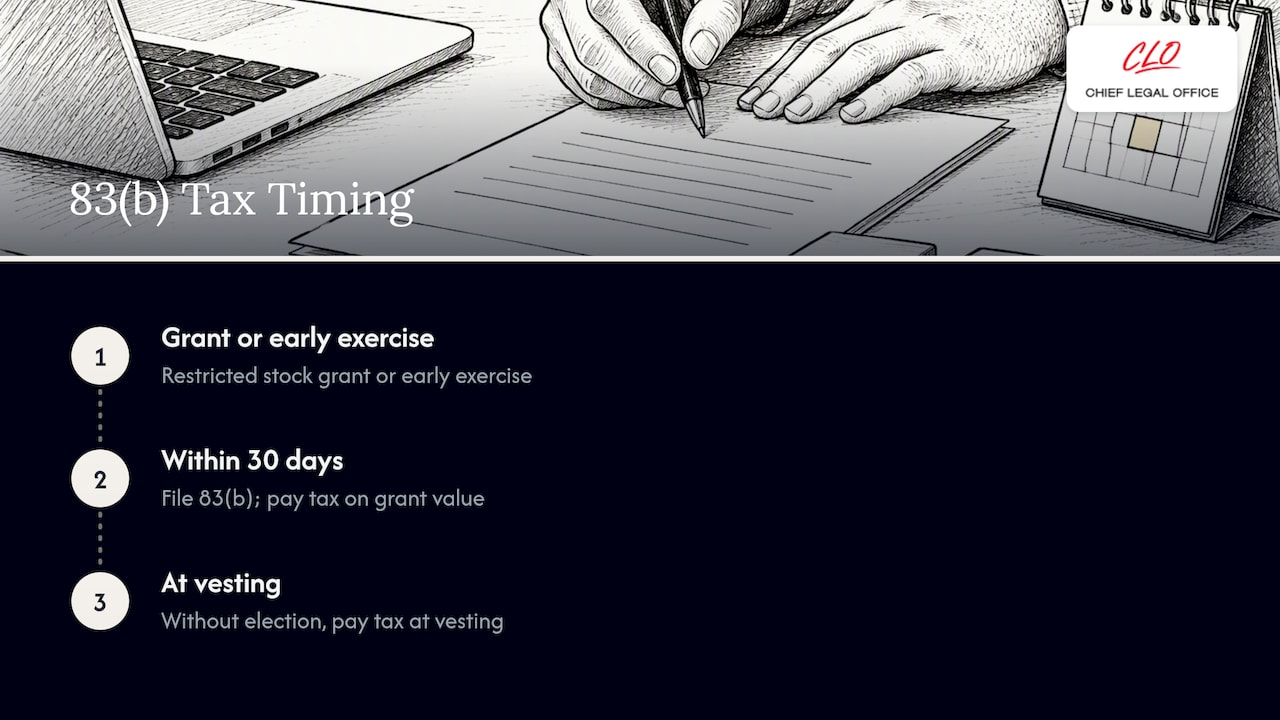
An 83(b) election, filed within 30 days of a restricted stock grant or an early exercise, lets the recipient pay tax on the value at grant instead of waiting until vesting, according to practitioner guidance on stock option taxes. This matters most when the stock’s value is low at grant and expected to climb, because paying tax now on a small number locks in a lower bill than paying tax later on a much larger one. The election is irrevocable, and missing the 30-day window forecloses the option entirely. There’s no appeal process and no quiet extension.
Employers have their own exposure here too. Granting options below fair market value triggers penalties and tax complications under Section 409A, which is why most companies obtain an independent 409A valuation before setting an exercise price. Skipping that valuation to save money is one of the more expensive shortcuts a growing company can take.
Rule 701 and Form S-8: Keeping Equity Grants Within SEC Limits
Private companies rely on an exemption to issue equity without registering every grant with the SEC, and that exemption has a name and a ceiling worth knowing.
Rule 701 allows private companies to issue compensatory securities to employees, consultants, and advisors without registering under the Securities Act, while still carrying antifraud obligations, according to the SEC’s explanatory release on Rule 701. The exemption comes with a disclosure trigger: once aggregate sales under compensatory plans exceed the Rule 701 disclosure threshold in any 12-month period, the issuer must deliver additional financial and risk disclosures to recipients under Rule 701(e), as set out in the SEC’s final rule.
A few practical compliance points follow from this:
Private companies track cumulative grant value against the $10 million threshold, not just individual grants.
Once a company becomes an SEC reporting company, typically after an IPO, Form S-8 replaces Rule 701 as the registration vehicle for ongoing equity plans.
Counsel should be looped in well before the threshold is crossed, since preparing Rule 701(e) disclosures takes real lead time, not a same-week turnaround.
Payroll and HR should flag any unusually large grant batch so legal can check the running total before it closes.
Equity compensation payroll reporting carries its own mechanics once shares vest or options exercise, and getting the withholding and W-2 reporting right is a separate operational task from the securities exemption itself, as practical payroll guidance on equity compensation reporting lays out.
How We Review and Fix Equity Documentation
When we take on a company’s equity documentation, the workflow is consistent: identify the actual governing documents first, confirm the 409A valuation and award type match what’s in the plan, then flag any PTE, acceleration, or forfeiture language that’s vague or inconsistent. From there we advise on 83(b) timing and loop in tax counsel where the stakes warrant it, and we document the Rule 701 steps so the company has a clean record if a buyer or investor asks.
Our review process involves senior, experienced legal professionals supported by attorneys and paralegals who handle the detail work. A common fix: replacing vague “Cause” language or an unclear 90-day PTE window with precise, dated terms that hold up under scrutiny.
Post-Vesting Actions: Exercise, Payment, and Share Issuance
Vesting is not the finish line. Once options vest, the holder still has to exercise them, which means paying the exercise price through cash, a cashless exercise, or sometimes a net exercise where the company withholds shares to cover the cost.
For restricted stock and RSUs, vesting typically triggers automatic share issuance, though companies often withhold a portion of shares to cover tax obligations rather than requiring the employee to pay cash separately. The company’s transfer agent or cap table platform then records the issuance, and the holder should confirm the share class they’re receiving. Common stock and preferred stock carry different rights, particularly around dividends, liquidation preference, and voting, so a holder converting from options to common stock should understand exactly what they now own.
Exercise windows close fast after termination, often 90 days, so anyone leaving a company with vested but unexercised options needs to act before that window shuts. Missing it means forfeiting the equity entirely, regardless of how long it took to vest.
Compliance and Reporting Obligations Beyond 409A and Rule 701
Section 409A and Rule 701 get most of the attention, but they’re not the only ongoing obligations tied to an equity plan.
Issuers need to maintain accurate cap table records, update option pools as shares are granted or forfeited, and track aggregate issuances against both Rule 701 and any state securities exemptions that apply alongside the federal one. State “blue sky” filings sometimes apply even when Rule 701 covers the federal registration question, and missing one doesn’t get caught until a diligence process surfaces it.
Awardees have their own reporting duties. Option exercises and stock vesting generate specific tax forms, including Form 3921 for ISO exercises and Form 3922 for employee stock purchase plan transfers, both of which the company is responsible for issuing accurately and on time. Employees filing an 83(b) election must also send a copy to the IRS within the 30-day window and keep proof of mailing, since the company isn’t the one filing it on the employee’s behalf.
None of this is complicated in isolation, but it adds up fast once a company has multiple grant rounds, departing employees, and a financing round layered on top. That’s usually when gaps surface.
Amending Equity Agreements: What Changes and What It Takes
Equity plans and grant agreements aren’t static. Companies amend them to add shares to the option pool, adjust vesting terms for a specific hire, or update acceleration language after a board realizes the existing terms don’t fit an upcoming transaction.
Most equity plans specify who can amend them, usually the board, and whether an amendment needs shareholder approval depends on what’s changing. Increasing the total share reserve typically requires shareholder consent. Adjusting administrative terms usually doesn’t.
Amending an individual grant agreement is different from amending the plan itself. Changing a specific employee’s vesting schedule or exercise price after the fact can trigger Section 409A problems if it’s treated as a modification that affects the deferred compensation timing, so this isn’t something to handle with a quick side letter. Material changes should go through board approval and get reflected in an amended and restated grant agreement, not an email confirming “we’re good with the new terms.”
Employees and founders alike should assume that any verbal or informal modification to equity terms needs to show up in writing, signed, before it means anything in a dispute.
Fitting Equity Into the Broader Compensation Package
Equity compensation works best when it’s evaluated alongside salary, benefits, and other components, not as a standalone perk disconnected from the rest of the offer.
A lower base salary paired with a meaningful equity grant can make sense for an early employee betting on company growth, but that same trade looks very different for a later hire joining after multiple funding rounds have diluted the option pool and pushed the exercise price higher. Benefits packages, including health insurance and retirement contributions, also interact with equity decisions. Someone weighing an early exercise or an 83(b) election needs to understand their full tax picture for the year, not just the equity piece in isolation.
Companies designing compensation structures should treat the equity plan as one lever among several, coordinated with cash compensation bands and benefits tiers rather than bolted on afterward. When those pieces are designed separately, by different people, on different timelines, inconsistencies creep in that are expensive to fix once grants are already outstanding.
What Founders Should Prioritize Right Now
If you’re a founder with an active option pool, the three things worth checking this month are your 409A valuation’s current status, your PTE windows across all outstanding grants, and whether any pending restricted stock grants are approaching their 83(b) deadline. Waiting until a financing round forces the question is the expensive way to find out your documents don’t match your intentions.
— Amy Natasha Osteen
How We Help With Equity Compensation Agreements
We draft and review equity plans and grant agreements for growing technology companies, ensuring senior oversight on PTE windows, 409A coordination, and Rule 701 calculations to help prevent cap table issues.
Our work here typically includes:
Drafting or revising grant agreements and plan documents to close the gaps that cause disputes later.
Coordinating 409A valuations and flagging when a new grant needs a fresh one.
Tracking Rule 701 disclosure thresholds and preparing the required disclosures before the deadline arrives.
Ongoing legal operations support so your cap table, grant records, and compliance files stay current as you scale.
This work sits inside our broader Fractional General Counsel service, and pricing runs through our Foundations, Embedded Access, and Strategic Growth plans depending on how much ongoing support your company needs. If you want a straight answer on whether your current equity documents hold up, reach out to request a scoping call.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What’s the difference between restricted stock and RSUs?
Restricted stock is actual stock issued at grant, subject to vesting and a company buyback right if you leave early, which makes an 83(b) election relevant. RSUs are a promise to deliver shares later at vesting, with no stock issued upfront, so an 83(b) election generally doesn’t apply to them.
How long do I have to exercise stock options after leaving a company?
The post-termination exercise window is set by the specific grant agreement, and 90 days is a common default, though some companies extend it. Check your grant agreement directly, since this window varies company to company and missing it forfeits the vested equity.
What happens if I miss the 83(b) election deadline?
The election must be filed with the IRS within 30 days of the grant or early exercise, with no extensions available, according to IRS guidance. Missing the window means you’ll owe tax based on the stock’s value at vesting instead of its lower value at grant, which can mean a significantly larger tax bill.
Does my offer letter or the formal grant agreement control my equity terms?
The formal equity plan and grant agreement generally control over an informal offer letter when the two conflict, based on how these documents are structured and enforced. If your offer letter promises something the grant agreement doesn’t reflect, that discrepancy should get resolved in writing before you rely on it.
When does a private company need to worry about Rule 701 disclosure requirements?
Once a company’s aggregate equity sales under compensatory plans exceed $10 million in any 12-month period, Rule 701(e) requires additional financial and risk disclosures to recipients, under the SEC’s final rule. Companies approaching that threshold should loop in counsel early since preparing the required disclosures takes real lead time.
Sources
Recommended
Founders and PE: Stop Tax Surprises From Rollover Equity Under ASC 805
3 Ready Change of Control Clauses for Founders and In House Counsel
The lawyerly fine print: This article is for general information, not legal advice…