The $10,000 Angel Check: Pro Rata Rights for U.S. Founders
Pro rata rights are contractual options, not obligations, that let an existing investor buy enough new shares in a future round to hold their ownership percentage steady on a fully diluted basis. They are usually offered to major investors, not everyone on the cap table. If you’re a founder, the move is to keep the scope narrow. If you’re an investor, the real decision is whether exercising is worth the capital.
TL;DR:
Pro rata allocations use fully diluted ownership, including options, warrants, notes, and SAFEs, then multiply that percentage by the new shares issued.
Set Major Investor thresholds around meaningful investment or ownership levels; tighter limits reduce coordination and legal costs, while terms vary widely and require negotiation.
Negotiate an exercise deadline, a cap on applicable future rounds, clear termination triggers, and explicit refill rights; resist super pro rata or attach a sunset.
Investors should compare the valuation, lead investor, syndicate quality, and reserve capital before exercising; if holders pass, refill terms let others take unused shares.
Chief Legal OfficeKeep Investor Rights in PerspectiveChief Legal Office provides a fractional in-house legal department to help technology companies manage investor rights alongside their wider legal function.Explore legal support
Table of Contents
How pro rata rights work: the mechanics behind the clause
Who actually gets pro rata rights
Negotiation points that protect your next round
Should you exercise? An investor’s decision framework
Worked example: the ownership math behind exercising or passing
A drafting checklist we use when reviewing investor rights
What founders and investors should do right now
How we help founders negotiate investor rights without the guesswork
FAQ
Sources
How pro rata rights work: the mechanics behind the clause
Pro rata rights sound simple until you have to calculate them, which is where most founders get tripped up during their first real negotiation.
The right is always measured on a fully diluted basis. That means you count every outstanding share, every option in the pool (granted or not), every warrant, and the shares that would convert from notes and SAFEs if they converted today. Leave any of that out and the percentage is wrong, which means the purchase right is wrong too.
The math itself follows a standard path:
Calculate the investor’s current fully diluted ownership percentage.
Multiply that percentage by the total number of new shares being issued in the new round.
That product is the number of shares the investor is entitled to purchase to hold their percentage flat.
You’ll find this language in a few predictable places: the company’s Investors’ Rights Agreement, a standalone pro rata agreement, or baked into a SAFE as a side letter. The Y Combinator pro rata agreement form, referenced in SEC filings, is a common template that shows how these rights get documented and, just as important, how they terminate (often at a qualified financing, an IPO, or a change of control).
Most pro rata provisions typically include an “over-allotment” or “refill” mechanic that allows other pro rata holders to acquire any unclaimed allocations, helping to ensure the round fills. This keeps the company from scrambling for a new check just because one investor passed, and it rewards the investors who stayed in the game.
Who actually gets pro rata rights
Not every investor on your cap table gets this option, and that’s by design. Giving pro rata rights to a small angel who wrote a $10,000 check creates administrative headaches without much upside, since that investor’s allocation in the next round would be tiny anyway.
That’s why most financing documents limit pro rata rights to “Major Investors,” a defined term with its own threshold. According to Wilson Sonsini’s explanation of NVCA model documents, this limitation exists specifically to reduce the administrative burden of offering participation rights to every stockholder.
A few things to keep in mind when you set your own threshold:
Thresholds are typically tied to minimum investment amounts or ownership percentages. Setting tighter thresholds reduces the number of investors involved in future rounds, saving coordination time and legal fees. These terms vary widely, so any “standard” figure should serve as a negotiation starting point rather than a fixed rule.
Negotiation points that protect your next round
Here’s where the real work happens. Pro rata rights are easy to grant in the excitement of closing a round and expensive to live with two years later when you’re trying to build a clean cap table for a new lead investor.
A few levers worth using:
Set a clear Major Investor threshold so only meaningful check-writers get the right.
Add a “use it or lose it” window so investors must exercise within a defined period or forfeit the allocation for that round.
Cap the number of future rounds the right applies to, instead of granting it in perpetuity.
Push back hard on “Super Pro-Rata” requests, where an investor wants to buy more than their existing percentage. Brown Rudnick’s term-sheet guidance is direct about this: Super Pro-Rata is not a market term, and founders should resist it or, if granted, attach a sunset clause.
Pay-to-play provisions are worth considering too. They penalize investors who don’t participate in a down round (often by converting their preferred shares to common), which protects the company from investors who want upside protection without putting in new money.
Pro Tip: Negotiate pro rata thresholds and caps before you negotiate valuation. It’s a smaller fight now and a much bigger one later.
Should you exercise? An investor’s decision framework
If you’re the investor, pro rata rights hand you a choice, not a requirement, and that choice deserves more thought than most people give it.
Reasons to exercise generally come down to protecting your position: maintaining your ownership stake, avoiding the dilution that comes with sitting out, and in some cases preserving the voting or information rights that are tied to a minimum ownership threshold.
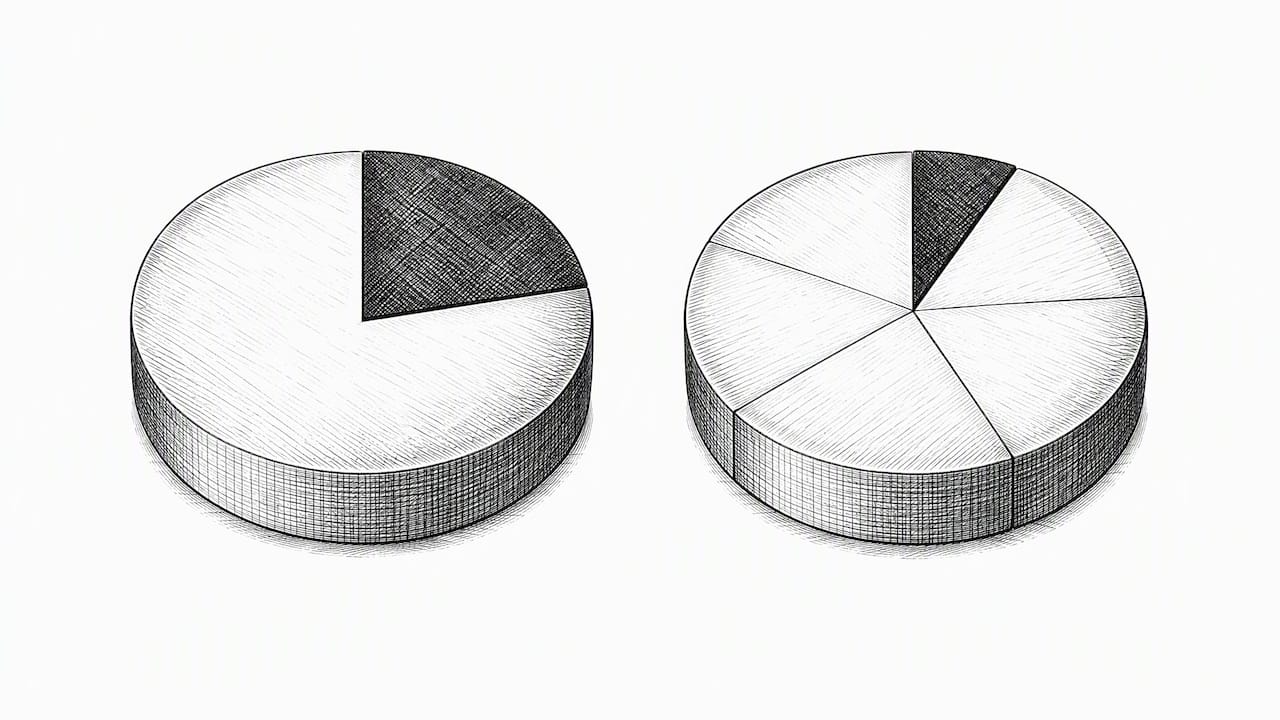
Reasons to pass are just as real. A round with weak terms, an inflated valuation, or a syndicate you’re not confident in might mean your reserve capital works harder somewhere else in your portfolio.
Before committing more money, run through this:
Has the valuation moved in a way that makes the new round attractive relative to your entry price?
Who’s leading the round, and do you trust their diligence?
Is the rest of the syndicate strong, or are you the only one showing up?
Do you have enough reserve capital to exercise here and still support your other portfolio companies?
Coordinate with co-investors early. If several major investors decline, the refill mechanic matters more, and the company will likely come back to the ones who exercised to ask if they’ll take a larger allocation.
Worked example: the ownership math behind exercising or passing
Numbers make this concrete, so let’s walk through an example.
The investor’s pro rata allocation is 10% of 2,000,000, or 200,000 shares.
If they exercise in full, they buy all 200,000 shares and their ownership percentage stays at 10% after the round closes.
If they exercise partially, their stake dilutes somewhat but remains closer to their original percentage; if they decline entirely, their stake dilutes more significantly once the round completes.
One sourced reference point worth keeping in mind: standard pro-rata provisions typically grant investors the option, not the obligation, to buy enough shares to maintain their existing percentage ownership on a fully diluted basis, as described in Brown Rudnick’s term-sheet materials. That single sentence is the entire concept. Everything else is math and negotiation.
If an investor passes and the allocation goes unclaimed, the over-allotment mechanic lets other major investors absorb it, which is often what keeps a Series B from falling short of its target. The takeaway for founders: build refill language into your agreement from the start, so one investor’s decision never threatens your round.
A drafting checklist we use when reviewing investor rights
When we’re reviewing a term sheet or investors’ rights agreement for a client, we start with the same reference points every experienced in-house team uses. The NVCA model Investors’ Rights Agreement is the baseline most U.S. venture deals are drafted against, and SEC-filed exhibits, like the sample pro rata agreement referencing SAFEs and conversion mechanics, show how these clauses actually get implemented once a deal closes.
A short checklist worth running before you sign anything:
Confirm the Major Investor threshold matches your actual cap table, not a template default.
Check whether the right has a sunset provision or applies indefinitely.
Look for Super Pro-Rata language disguised as a standard allocation.
Verify the refill mechanic is explicit, not assumed.
Make sure termination triggers (IPO, acquisition, qualified financing) are clearly defined.
Treat pro rata as a gating item in the negotiation, as Cooley GO points out about investor protective provisions generally: easy to grant in the moment, costly in cumulative effect if you don’t set boundaries early.
What founders and investors should do right now
If you’re raising, set your Major Investor threshold and reserve allocation before your term sheet gets drafted, not after. If you’re investing, write down your exercise criteria now, before the next hard decision lands in your inbox. Either way, get counsel involved before you sign.
— Amy Natasha Osteen
How we help founders negotiate investor rights without the guesswork
Pro rata negotiations move fast, and the clause that seemed minor in your seed round can become the thing blocking your Series C lead from getting the allocation they want. We have legal teams experienced in these negotiations who review term sheets, draft investors’ rights agreements, and manage communications with investor counsel so you’re not translating legal language under deadline pressure.
Our Capital Raises and M&A service covers exactly this kind of work, and it connects directly to the ongoing support available through our Foundations, Embedded Access, and Strategic Growth plans. If you want a legal team that already knows your cap table before your next round starts, reach out and we’ll walk you through how the engagement works.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What does pro rata ownership mean?
Pro rata ownership means an investor holds the right to maintain their existing percentage stake in a company by purchasing a proportional number of new shares in a future financing round. It’s calculated on a fully diluted basis, which includes options, warrants, and convertible securities, not just outstanding common and preferred shares.
Are rights offerings good or bad?
Rights offerings, including pro rata rights, aren’t inherently good or bad: they’re a negotiated allocation of future investment opportunity. For founders they can create administrative complexity if granted too broadly, while for investors they offer a tool to protect ownership against dilution, so the right approach depends on how the terms are scoped.
What is the 2:20 rule in venture capital?
Fund manager compensation is distinct from how pro rata rights work between a fund and a portfolio company.
What is the 10% investor rule?
Any threshold should be confirmed in the company’s actual investors’ rights agreement rather than assumed from a general rule of thumb.
Sources
What are the NVCA model legal documents? | Wilson Sonsini (NVCA reference)
Pro Rata Agreement (SEC exhibit referencing Y Combinator form)
Consider control and voting rights when making venture capital deals | Cooley GO
Recommended
Founders: Sign an IP Assignment Agreement Now Before Fundraising
Founders and PE: Stop Tax Surprises From Rollover Equity Under ASC 805
6 Buckets Investors Expect: Data Room Checklist for Founders & Legal
3 Ready Change of Control Clauses for Founders and In House Counsel
The lawyerly fine print: This article is for general information, not legal advice…